Prabhdeep Gill
Reveal Menu
Market Commentary: Monthly Bulletin October 2026
Key Points
(All figures are based on bid‑bid prices with income reinvested unless otherwise stated)
The AI Trade Comes Under Pressure
After months of powering markets higher, the enthusiasm for artificial intelligence finally paused for breath in October. Midway through the month, shares in the big technology and chip making companies fell sharply, with an estimated $1 trillion wiped off the value of AI-related stocks in a matter of days. Two things unsettled investors, growing questions over whether the enormous sums being poured into AI will ever generate the profits that today’s share prices assume and secondly worries about how all that spending is being funded.
Because so much of the market’s rise this year had been concentrated in a relatively small number of these names, when they stumbled, the effect was felt widely. It was a classic reminder that the areas which rise fastest can also fall hardest.
Asia and Emerging Markets Bear the Brunt
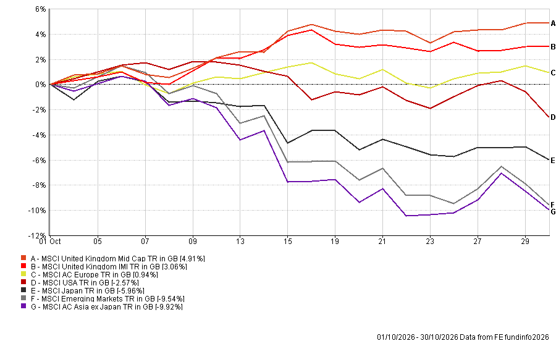
The pain was felt most acutely in Asia and the emerging world. The companies that manufacture the advanced computer chips at the heart of the AI boom are concentrated in markets such as South Korea and Taiwan, so when sentiment towards AI soured, these markets fell the furthest. Emerging Markets dropped 9.54% over the month and Asia excluding Japan fell 9.92%, while Japan declined 5.96% and the US slipped 2.57%. For these regions it was a sharp setback after a very strong run earlier in the year, and it handed back a large chunk of the gains they had built up. This is the flip side of the strong returns Asia and emerging markets had delivered, markets that are closely tied to a single powerful theme tend to move further in both directions.
Inflation, Interest Rates and a UK Safe Haven
The spark for the sell off was a hotter than expected US inflation reading, which revived fears that interest rates may need to rise further rather than fall. Higher for longer interest rates are particularly unwelcome for fast growing, expensive companies, exactly the sort that dominate the AI trade because more of their value rests on profits far in the future.
As investors looked for shelter, they turned towards steadier, cheaper and more defensive parts of the market, and this is where the UK came into its own. With relatively little exposure to technology and a greater weighting in ‘old economy’ businesses such as energy, banks and consumer goods, the UK market rose while others fell, the broad UK index gained 3.06% and medium sized UK companies 4.91%, with Europe also modestly positive at 0.94%. Having often been overlooked during the AI-driven rally, the UK’s steady, value dividend paying character proved its worth just when it was needed.
Portfolio Positioning
October was an uncomfortable month in places, but it was also an instructive one. It showed how quickly market leadership can switch, and why we spread clients’ investments across regions and styles rather than chasing whichever theme is in favour. A portfolio concentrated in this year’s winners would have felt October’s falls, whereas a diversified one was cushioned by the strength of the UK and Europe.
None of these changes the long-term promise of AI, but it is a healthy reminder that prices can run ahead of reality and that corrections are a normal part of investing. In keeping with our ‘protect and participate’ approach, we remain well diversified positioned to benefit from the opportunities ahead while cushioning the inevitable bumps along the way. As always, we are monitoring events closely and will adjust positioning as conditions evolve.
BOOLERS INVESTMENT COMMITTEE